
Introduction
Made a budget on the 1st of the month, felt motivated for about ten days, and then completely abandoned it by the 15th? You’re definitely not alone there. Most people fail at budgeting not because they lack discipline, but because they never really learned how to create a monthly budget that matches their actual life instead of some idealized version of it. Let’s fix that.
Why Most Budgets Fail Within Weeks
The usual problem is unrealistic category limits set on day one, based on hope rather than actual past spending data. If you’ve never tracked your food delivery spending and randomly set a ₹2,000 limit when you actually spend ₹6,000, the budget breaks almost immediately — and once it breaks once, most people give up entirely.
Step 1: Track Before You Budget
Quick answer: The first real step in how to create a monthly budget that works is tracking your actual spending for at least one full month before setting any limits, so your budget is based on real numbers, not guesses.
Step 2: Categorize Your Expenses Honestly
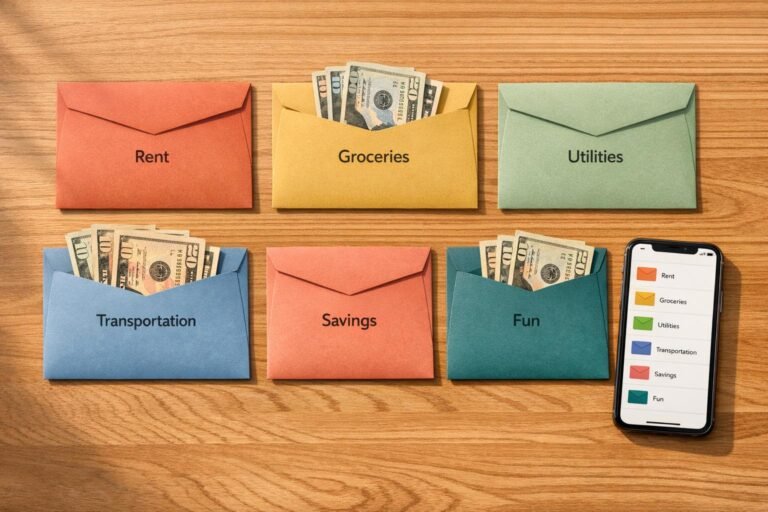
Break your spending into clear categories — don’t lump everything into “miscellaneous,” since that category becomes a black hole where all your budgeting insight disappears.
- Fixed needs — rent, EMIs, insurance, utility bills
- Variable needs — groceries, fuel, basic transport
- Wants — dining out, shopping, entertainment, subscriptions
- Savings and investments — SIPs, emergency fund contributions
Step 3: Use a Framework, But Adapt It to Your Reality
The 50/30/20 rule [link to related guide on the 50/30/20 budget rule here] is a solid starting framework, but don’t force your numbers into it if your city’s rent genuinely eats up 45% of your income. Adjust the percentages to fit your real constraints, then work toward the ideal ratio gradually as income grows.
Step 4: Set Category Limits Based on Actual Data, Not Aspiration
Once you’ve tracked a month, set limits slightly below your actual current spending in flexible categories (wants) rather than drastically cutting them overnight. A 10-15% reduction target feels achievable; a 50% cut feels punishing and usually fails within days.
Step 5: Build in a Buffer for Irregular Expenses
This is the part people forget most often — annual expenses like insurance premiums, festival spending, or an occasional big purchase don’t fit neatly into a monthly view. Set aside a small “irregular expenses” category each month (even ₹1,000-2,000) so these don’t blow up your budget when they hit.
Step 6: Automate What You Can
Set up auto-transfers for savings and SIPs right when salary arrives, and auto-pay for fixed bills. This way, the “savings” and “needs” portions of your budget happen automatically, and you only need to actively manage the more flexible “wants” category day to day.
Step 7: Review and Adjust Monthly, Not Just Once
A budget isn’t a one-time setup — review it every month, see where you overshot or undershot, and adjust the following month’s limits accordingly. Life changes (a new EMI, a salary hike, a move to a new city) should reflect in your budget within a month or two, not stay outdated for years.
A Realistic Example
Picture someone earning ₹45,000 monthly in Jaipur, having tracked one month of spending:
- Fixed needs: ₹18,000 (rent, bills)
- Variable needs: ₹8,000 (groceries, transport)
- Wants: ₹10,000 (dining, shopping, subscriptions — trimmed slightly from ₹12,000 actual)
- Savings: ₹9,000 (SIP and emergency fund)
Notice the wants category was trimmed gradually, not slashed in half — that small, realistic reduction is far more sustainable long-term.
Tools to Help You Stick With It
You don’t need anything complicated — a simple spreadsheet works fine for many people, though budgeting apps [link to related guide on best budgeting apps here] can automate the tracking part if manual entry feels like too much friction.
FAQ
How to create a monthly budget if my income varies every month? Base your fixed and variable needs on your lowest-earning month from the past 6-12 months, and treat any extra income in higher-earning months as a bonus for savings or discretionary spending.
Should I include debt repayment as a separate budget category? Yes, especially if you have any high-interest debt like credit card balances — treat minimum payments as a fixed need and any extra repayment as part of your savings/debt-reduction category.
How often should I revise my monthly budget? Review it every month for small adjustments, and do a more thorough revision every 6 months or after any major life change like a job switch, move, or new financial goal.
Is it normal to go over budget in the first few months? Yes, completely normal — budgeting is a skill that improves with practice. Use early overshoots as data to refine your category limits rather than as a reason to give up entirely.
What’s the biggest mistake people make when learning how to create a monthly budget? Setting limits based on hope rather than actual tracked spending data, which almost guarantees the budget breaks within the first couple of weeks.
Conclusion
Learning how to create a monthly budget that actually sticks comes down to tracking first, setting realistic limits based on real data, and reviewing regularly rather than setting it once and forgetting it. Give yourself grace in the first couple of months — the goal is steady improvement, not instant perfection. [link to related guide on 10 practical ways to save money on a low salary here] if your budget review shows you need to trim spending further.
Suggested Alt Text: “Notebook and calculator showing monthly budget categories with spending amounts”